Misaligned contracts
Your purchase contract references one quotation period, while your sales contract references another, often with a fixed price. You pay the difference with every fluctuation, in either direction.
CONSULTING FOR THE ALUMINIUM INDUSTRY
I help industrial buyers of semi-finished aluminium products control their LME price exposure and protect their margins.
A discovery call, no commitment.
THE SUBJECT
The price you pay for a semi-finished aluminum product is a composite: it comprises an LME quote, a regional premium, and a processing spread, as well as a quotation period and an indexation clause. Each component fluctuates at its own pace. Your selling prices, meanwhile, are subject to different constraints, such as annual tarif or project specific pricing. And when purchasing and sales do not follow the same rules, your margins are inevitably affected.
Your purchase contract references one quotation period, while your sales contract references another, often with a fixed price. You pay the difference with every fluctuation, in either direction.
Positions are taken on a case-by-case basis, without a mandate, thresholds, or a record of decisions. When the decision maker leaves, the expertise leaves with them.
Base price, regional premium, processing, transport, energy, carbon. Two supplier quotes from the same day cannot be compared if they are based on different criteria.
A recycled content rate requested by customers or mandated by regulations affects material availability, premium levels, and even the choice of supplier. These three factors can be anticipated.
MAIN OFFER
The goal is not to forecast LME prices. No one does that reliably and I make no such claim. The goal is to make your exposure measurable, decide what portion to hedge, and establish a system capable of managing that decision over time.
I work with finance, purchasing and executive management teams, on your contracts, your volumes and your timeframes. Not on a generic model.
What you receive:
OTHER WORK
Break down your costs line by line: LME price, regional premium, spread, logistics, energy, and carbon. This allows you to compare offers that are not otherwise directly comparable and to distinguish the negotiable portion of your price from the non-negotiable portion.
Translate recycled content requirements into quantifiable impacts: material availability, premium differentials, effects on the declared carbon footprint, and appropriate indexation formulas. The data used comes from your suppliers' environmental declarations or, failing that, from official European Aluminium Association datasets.
METHOD
Scope, deadlines, and the decision expected at the end of the assignment.
Interviews with the functions concerned, collection of contracts and volumes, mapping of net exposure.
Costed scenarios, cash sustainability test, choice made by your executive committee.
Mandate, runbook, pilot trade, dashboard, training of your teams.
Every assignment is billed as a fixed fee. You know the content and the amount before we start. No daily rates, no duration drift.
OPEN ACCESS
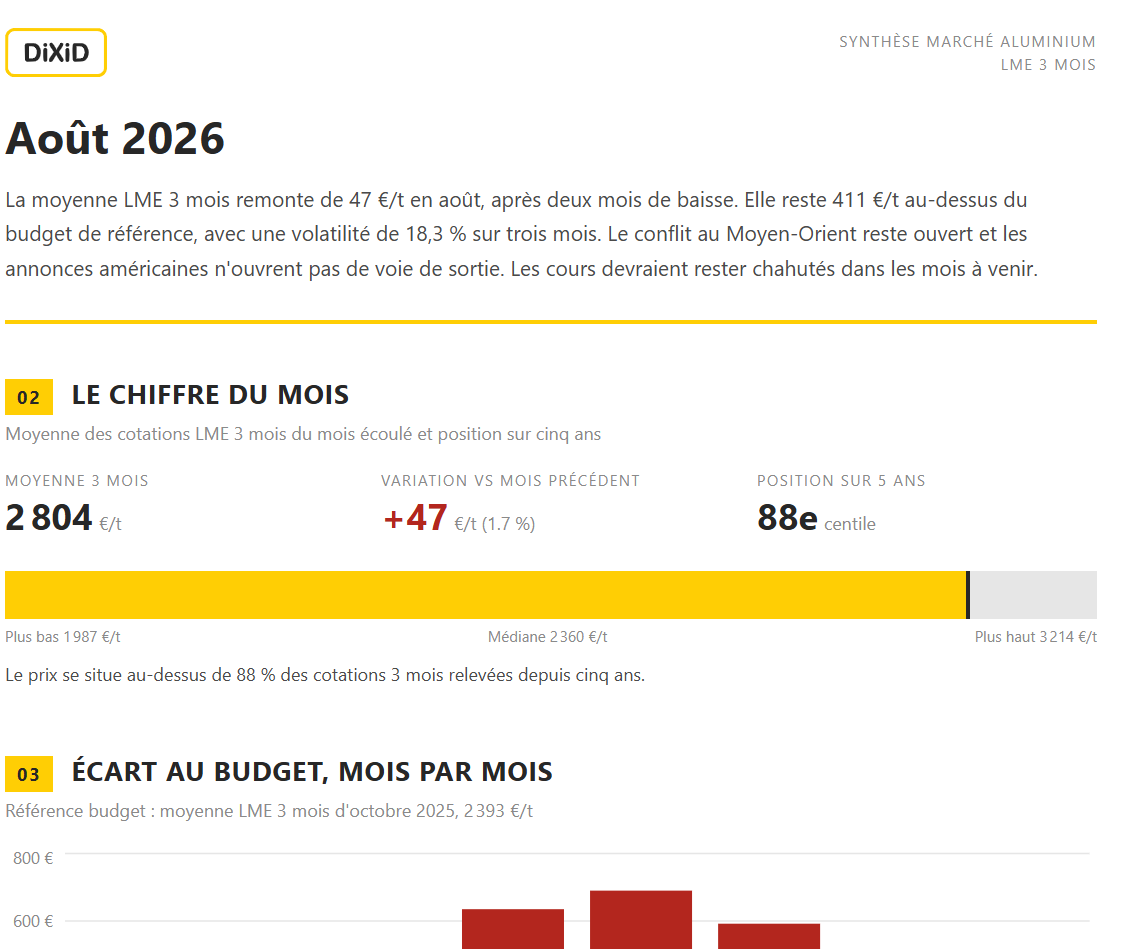
An online tool that calculates what an LME move does to your margin, from your volumes and your maturities. It applies the method I use on assignments: breakdown by sub-period, margin at risk thresholds, readings in euros and in EBITDA points. Nothing to install, just a click on a link.
Open the toolWORK DELIVERED
WHO I AM
I spent 17 years in the aluminium industry, in production, in sales and on the executive committee of a major player in the sector. I bought and sold LME indexed aluminium, negotiated contracts, and managed price exposure in tight market conditions.
I founded DiXiD to put that experience to work for the industrial companies that transform or buy aluminium. My target: European companies consuming semi-finished aluminium products (extrusions, sheet, castings) from 250 tonnes a year, in construction, transport, solar, electrical products, stockholding and general engineering.
What I deliver comes down to one line: the system and the information needed to decide.
FREQUENTLY ASKED QUESTIONS
The answers below reflect the way I work. They do not replace a conversation about your own situation.
By measuring the exposure first, not by buying a financial instrument. You establish the net position month by month, in tonnes and in euros, then align whatever can be aligned in supplier and customer contracts: quotation period, index, currency. Financial hedging only comes afterwards, on the share of exposure management decides to cover.
The LME price is the global exchange-traded price of the metal, and it can be hedged with financial instruments. The regional premium pays for physical delivery of metal into a given region. It moves at its own pace, does not follow the quotation and is not hedged the same way. Confusing the two makes any offer comparison unreliable.
It is the price paid once everything is added up: LME quotation, regional premium, processing spread, transport, energy and carbon. Two quotes issued on the same day are not comparable if they assemble these components differently. Breaking down the all-in price separates the negotiable part of your price from the part that is not.
I work with European companies consuming semi-finished aluminium products (extrusions, sheet, castings) from 250 tonnes a year, in construction, transport, solar, electrical products, stockholding and general engineering. Below that, the exposure exists but the machinery required is rarely proportionate.
By putting both contracts side by side: quotation period, reference index, currency, pricing date, indexation clause. The gap between the two sets of rules is where the exposure comes from. Part of it is corrected through contract negotiation, which costs less than financial hedging. What remains becomes the position to hedge.
Financial hedging ties up cash: a security deposit when the position is opened, margin calls when the market moves against it. That is why every scenario I deliver is quantified in a best case and a worst case, with its cash effect, and tested for sustainability before any decision is made.
By translating the required rate into three measurable consequences: material availability, premium differential, effect on the declared carbon footprint, then adapting the indexation formula. The data used comes from your suppliers' environmental declarations or, failing that, from official European Aluminium Association datasets.
No. No one does that reliably and I make no such claim. The work covers what can be controlled: measuring the exposure, the share that is hedged, the decision rules and the follow-up over time.
In four stages: framing, diagnosis, decision, implementation and handover. It ends with a signed mandate, a runbook, a pilot trade at reduced tonnage and a dashboard run by your own teams. Every assignment is billed as a fixed fee: content and amount known before we start, no daily rate.
GET IN TOUCH
Thirty minutes to understand your situation and tell you how I can help you. If I cannot, I say so before the call ends.
Pick a slot
Send a message